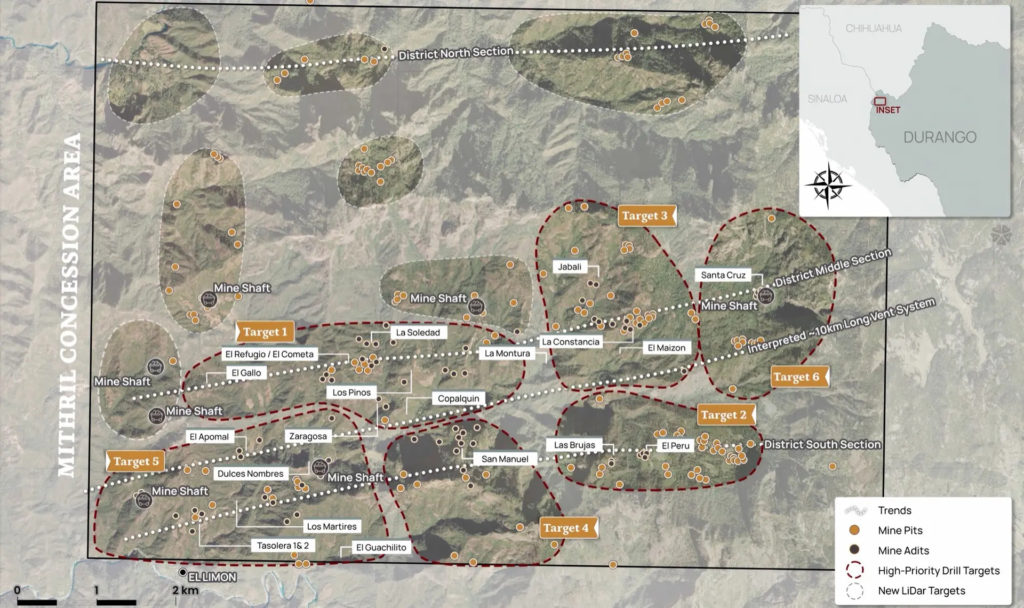
Stormlands Mining has released a model for Mithril Silver and Gold’s (CVE: MSG) Copalquin gold-silver property in Durango, Mexico. The study lifts the site’s net present value (NPV) to $613.5 million (C$860.44 million) after applying current gold and silver prices to its April mineral resource estimate (MRE).
Located in northwestern Mexico, in the Sierra Madre gold-silver trend, the Copalquin mining district covers 70 square-kilometres and contains several dozen historic gold and silver mines.
“Copalquin is particularly interesting because the latest resource estimate already incorporates practical underground mining constraints, giving us a stronger basis for preliminary economic modelling than a conventional exploration-stage resource,” said Róisín O'Connell, Stormlands’ co-founder and CEO. “The model shows strong margins under the commodity prices used in the technical report, but the sensitivity work is equally important. It shows very clearly where the value is coming from and how the economics respond when the assumptions change. Gold is the dominant driver.”
Without a formal preliminary economic assessment (PEA) Stormlands’ model instead uses the project’s 2026 MRE. While Stormlands’ data modeling demonstrates Copaquin’s sensitivity to gold pricing, it does not replace the engineering, cost work and risk analysis required for a full PEA.
Revenue jump
Stormlands’ base model produced an NPV of $$396.3 million at a 5% discount rate before Stormlands applied a gold price of $4,398.80 per ounce and a silver price of $66.36 per ounce, increasing the valuation by almost 55%.
The higher metal prices raised projected life-of-mine revenue to about $1.79 billion from $1.35 billion. Earnings before interest, taxes, depreciation and amortization (EBITDA) went to $1.45 billion from $1.01 billion.
The project’s internal rate of return (IRR) rose to 92.23% from 64.15% in the base model.
Library of resources
The case study is part of the Stormlands’ library series, a set of resources for mining companies to predict and assess economic conditions. Recent studies examined the Odienné, Kinsley and Fremont projects.

Comments